Snowball vs. avalanche: which is better?
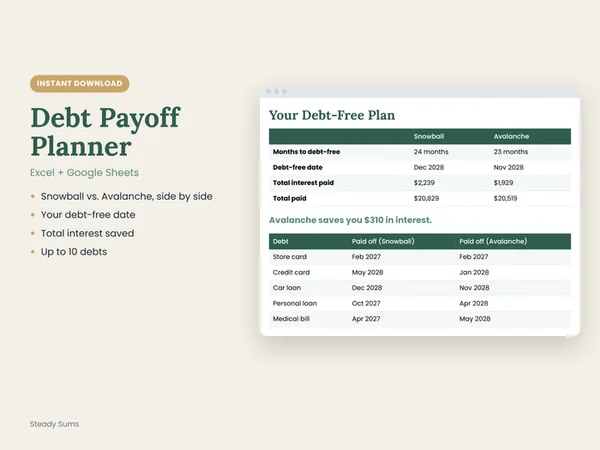
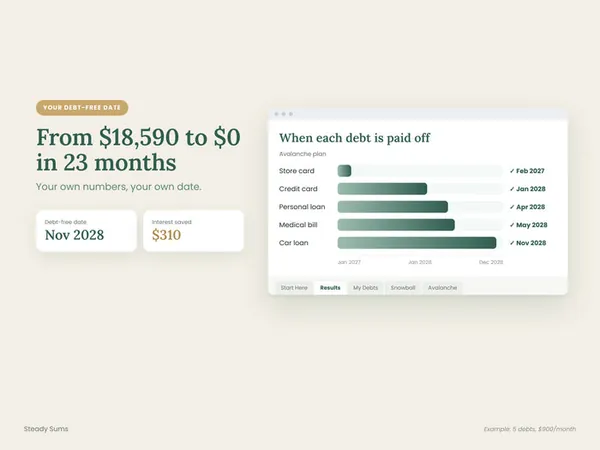
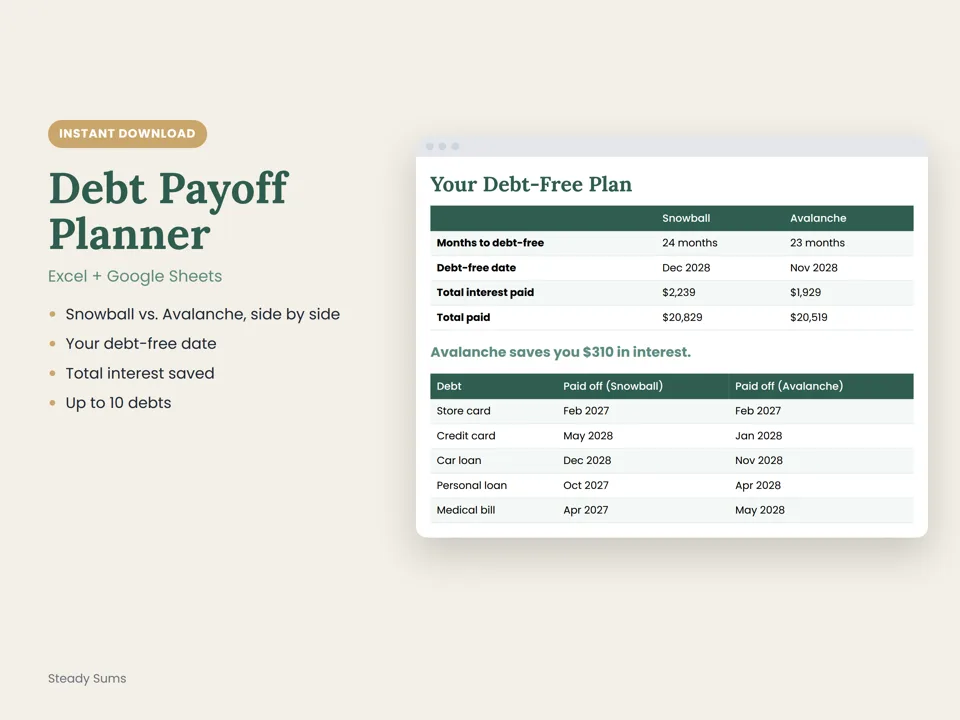
Both methods have you pay the minimum on every debt and put every extra dollar toward one target debt. When that debt is gone, its payment rolls into the next one, so your payoff speed keeps growing.
Avalanche targets the highest interest rate first. It's the math-optimal choice and usually saves the most money. Snowball targets the smallest balance first. You pay off whole debts sooner, and those early wins keep a lot of people motivated.
How to use your results
- Pick a method. If the savings difference is small, choose snowball for motivation.
- Set every debt to autopay its minimum.
- Schedule your extra payment toward debt #1 on payday.
- When a debt is paid off, add its payment to the next one on the list.
Go deeper: Debt snowball vs. avalanche: which should you use?
Questions people ask
What is APR?
APR (annual percentage rate) is the yearly interest rate on a debt. You can find it on your statement. Credit cards are often 20–30%, while car loans and mortgages are usually much lower.
Should I save or pay off debt first?
Many people keep a small emergency fund (often $1,000) before attacking debt, so a surprise expense doesn't go back on a credit card. After that, high-interest debt usually comes first.
Is this calculator exact?
It's a close estimate. It assumes interest is charged monthly at your APR and that your payments stay the same. Real statements vary slightly because of daily interest and fees.